What is the scope and industry significance of the Vitamin-Fortified Beverages Market?
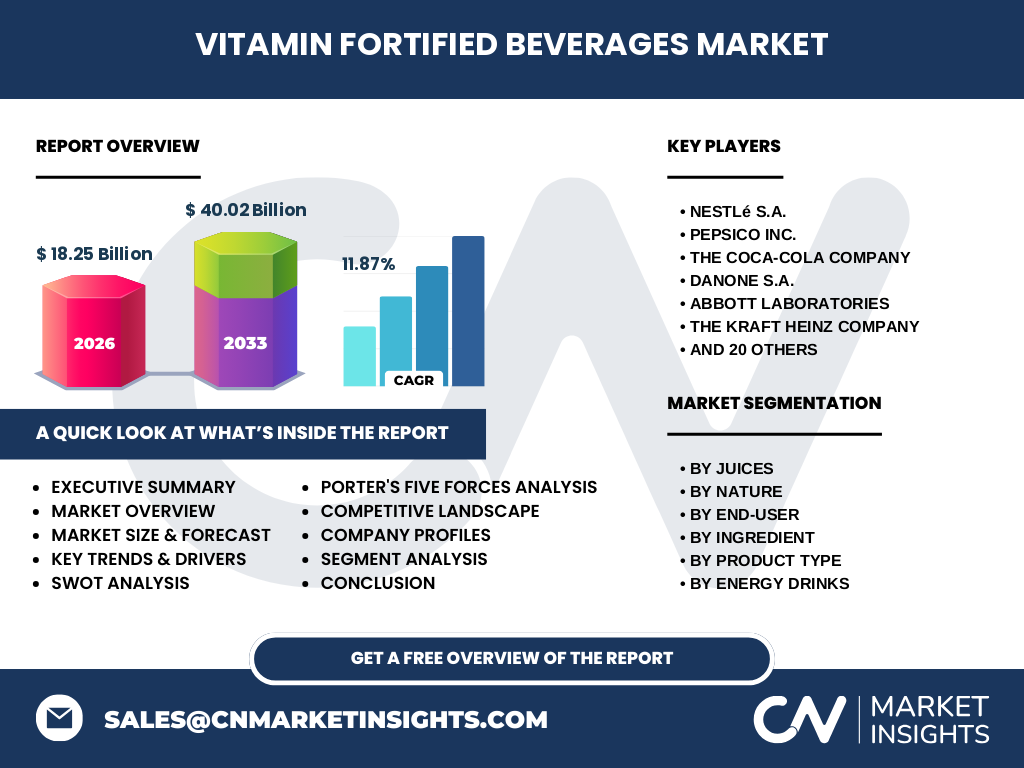
Our analysis indicates that the Vitamin-Fortified Beverages Market represents a transformative sector within functional nutrition, valued at 18.25 Billion in 2026. This industry encompasses functional liquids enriched with essential micronutrients like Vitamin C and Vitamin D, navigating complex regulatory frameworks enforced by the U.S. FDA and EFSA to meet surging consumer demand for preventative healthcare solutions.
Key market drivers, restraints, challenges, and opportunities shaping the Vitamin-Fortified Beverages Market
The market is propelled by rising chronic lifestyle diseases and post-pandemic immunity prioritization. However, formulation stability challenges—particularly preventing vitamin degradation during thermal pasteurization—act as key restraints. Growth opportunities lie in utilizing cold-pressed processing techniques for Cold Pressed Vitamin Fortified Juices, allowing brands like The Coca-Cola Company and PepsiCo Inc. to capture high-margin health-conscious demographics.
Emerging trends and growth patterns in the Vitamin-Fortified Beverages Market
Clean-label formulations and plant-based matrices are dominating industry trends. Consumers increasingly favor Plant-Based Vitamin Beverages and Natural Flavor Vitamin Water over synthetic alternatives. This shift forces supply chains to source transparently, driving innovations in aseptic bottling and cold-chain logistics to maintain nutrient integrity without artificial preservatives.
How did the COVID-19 pandemic impact the Vitamin-Fortified Beverages Market and its recovery trajectory?
The pandemic served as a massive catalyst, permanently altering consumer health awareness and accelerating functional beverage adoption. Supply chain disruptions at major ports initially stalled raw material delivery for water-soluble vitamins, but aggressive post-pandemic recovery strategies by Nestlé S.A. and Danone S.A. stabilized output, cementing fortified drinks as daily wellness staples.
Competitive landscape: major players, market concentration, and strategic dynamics
The market exhibits a moderately consolidated structure, dominated by multinationals like Monster Beverage Corporation, Red Bull GmbH, and Keurig Dr Pepper. Strategic dynamics revolve around aggressive M&A activity, where industry giants acquire agile disruptors in the Probiotic Vitamin Drinks space to rapidly expand their functional portfolios and distribution footprints.
Executive summary of key findings in the Vitamin-Fortified Beverages Market report
Our research forecasts the Vitamin-Fortified Beverages Market to expand significantly from 2027 to 2033, achieving an impressive 11.87% CAGR to reach 40.02 Billion by 2033. Growth is anchored by surging demand for Electrolyte And Vitamin Sports Drinks and Organic ingredient certifications across retail channels.
Market forecast and projected growth trajectory from 2027 to 2033
Starting from a baseline of 18.25 Billion in 2026, the sector is projected to surge to 40.02 Billion by 2033 at a robust 11.87% CAGR. This accelerated expansion is fueled by rising disposable incomes in emerging economies and the mainstreaming of preventive wellness products across traditional supermarket chains.
Segmentation analysis across juices, nature, end-users, ingredients, product types, and distribution
Segmentation reveals nuanced consumer preferences across multiple axes. Product categories span Energy Drinks, Flavored Water, and Ready-To-Drink Teas And Coffees. Ingredients are led by Vitamin C and Vitamin D additions, while distribution is split between supermarkets, Online Retail, and specialty health stores.
Regional market analysis and geographic performance distribution
Geographically, North America dominates consumption due to entrenched functional beverage habits and high retail penetration of Zero Calorie Vitamin Flavored Water. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, driven by expanding urban middle classes in China and Japan embracing Dairy Based Vitamin Beverages.
In-depth regional review of key growth territories
In North America, strict labeling guidelines by regulatory bodies dictate product claims, favoring established players with robust compliance divisions. Conversely, the European market prioritizes Organic and sustainable packaging, challenging manufacturers like HiPP GmbH & Co. Vertrieb KG to innovate eco-friendly bottling for Sparkling Vitamin Flavored Water.
Company profiles and strategic positioning of leading industry participants
Industry leaders utilize distinct competitive moats. Abbott Laboratories and Herbalife Ltd. focus on clinical-grade Nutritional Supplement Beverages targeting geriatric and adult demographics. Meanwhile, Celsius Holdings and Talking Rain Beverage Company capture younger consumers via targeted digital marketing for Caffeinated Vitamin Energy Drinks and Vitamin Infused Flavored Water.
Porter's Five Forces analysis of the competitive environment
Supplier power remains moderate due to the specialized sourcing required for pharmaceutical-grade micronutrients. However, threat of new entrants is high given low initial branding barriers in Flavored Water, though intense retail slotting fees enforced by major supermarket chains act as a formidable deterrent against unestablished micro-brands.
SWOT analysis highlighting strengths, weaknesses, opportunities, and threats
Key strengths include high brand loyalty and diverse product portfolios. Weaknesses involve high sensitivity to raw material price volatility for vitamins. Opportunities abound in emerging functional formats like Herbal Infused Vitamin Energy Drinks, while threats stem from tightening regulatory scrutiny regarding health claims on functional packaging.
Value chain analysis detailing industry structure and value flow
The value chain initiates with chemical and agricultural extraction of raw vitamins, followed by precision blending facilities managed by ingredient innovators. Value flows through high-speed aseptic bottling plants operated by giants like The Coca-Cola Company, ultimately terminating at omni-channel retail distribution networks reaching end-consumers.
Investment insights and high-potential strategic growth areas
Investors should direct capital toward specialized functional niches, particularly Probiotic Vitamin Drinks and Plant-Based Vitamin Beverages. Companies demonstrating agile supply chain resilience and compliance with strict functional food regulations offer the highest risk-adjusted return profiles over the 2027-2033 forecast period.
Conclusion and key takeaways for stakeholders
The Vitamin-Fortified Beverages Market offers immense profitability, underscored by an 11.87% CAGR pushing valuations to 40.02 Billion by 2033. Success requires balancing aggressive flavor innovation with uncompromised regulatory compliance, specifically within high-growth categories like Isotonic Vitamin Sports Drinks.
Research methodology and data triangulation practices
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data from import-export authorities, conducting primary stakeholder interviews with R&D heads at Nestlé S.A. and PepsiCo Inc., and analyzing secondary macroeconomic indicators including retail scanner data and disposable income metrics across target regions.
Scope of the report, coverage parameters, and analytical limitations
This report covers global consumption trends, regional forecasts, and granular product segmentations from 2026 to 2033. Limitations include potential unforeseen macroeconomic shocks or sudden regulatory shifts by agencies like the EFSA regarding maximum allowable micronutrient thresholds in commercial beverages.
Recent developments, strategic moves, and product launches across the sector
Recent market activity features aggressive portfolio expansions, such as Asahi Group and Suntory Beverage & Food Limited launching advanced functional formulations combining adaptogens with Vitamin Fortified Ready-to-Drink (RTD) Teas. Strategic partnerships between beverage conglomerates and biotech ingredient suppliers continue to redefine functional efficacy standards.